Buying your first home feels impossible. It usually isn’t.
I’m James Cox. I’m a licensed mortgage loan originator, and most of the people I help are buying their first home right here in Metro Detroit — usually assuming they need perfect credit and 20% down, and usually wrong about both.
One short phone call and you’ll know where you actually stand. Free, no credit check, no pressure, and no jargon. If you’re not ready yet, I’ll tell you that too, and exactly what would change it.
- Free 10-minute call, no obligation
- No credit check to talk
- FHA, VA and Conventional
- You talk to James, not a call center
Book your call
Takes 30 seconds. James calls you.
5 years
Helping buyers get to the closing table
Independent broker
Sponsored by The Loan Factory, NMLS# 320841
FHA · VA · Conventional
Purchase loans for first-time buyers
Metro Detroit
Wayne, Oakland and Macomb counties
Every buyer’s situation is different. I don’t run people through a template — I tailor your scenario individually and find the benefit in your circumstances, wherever you’re starting from.
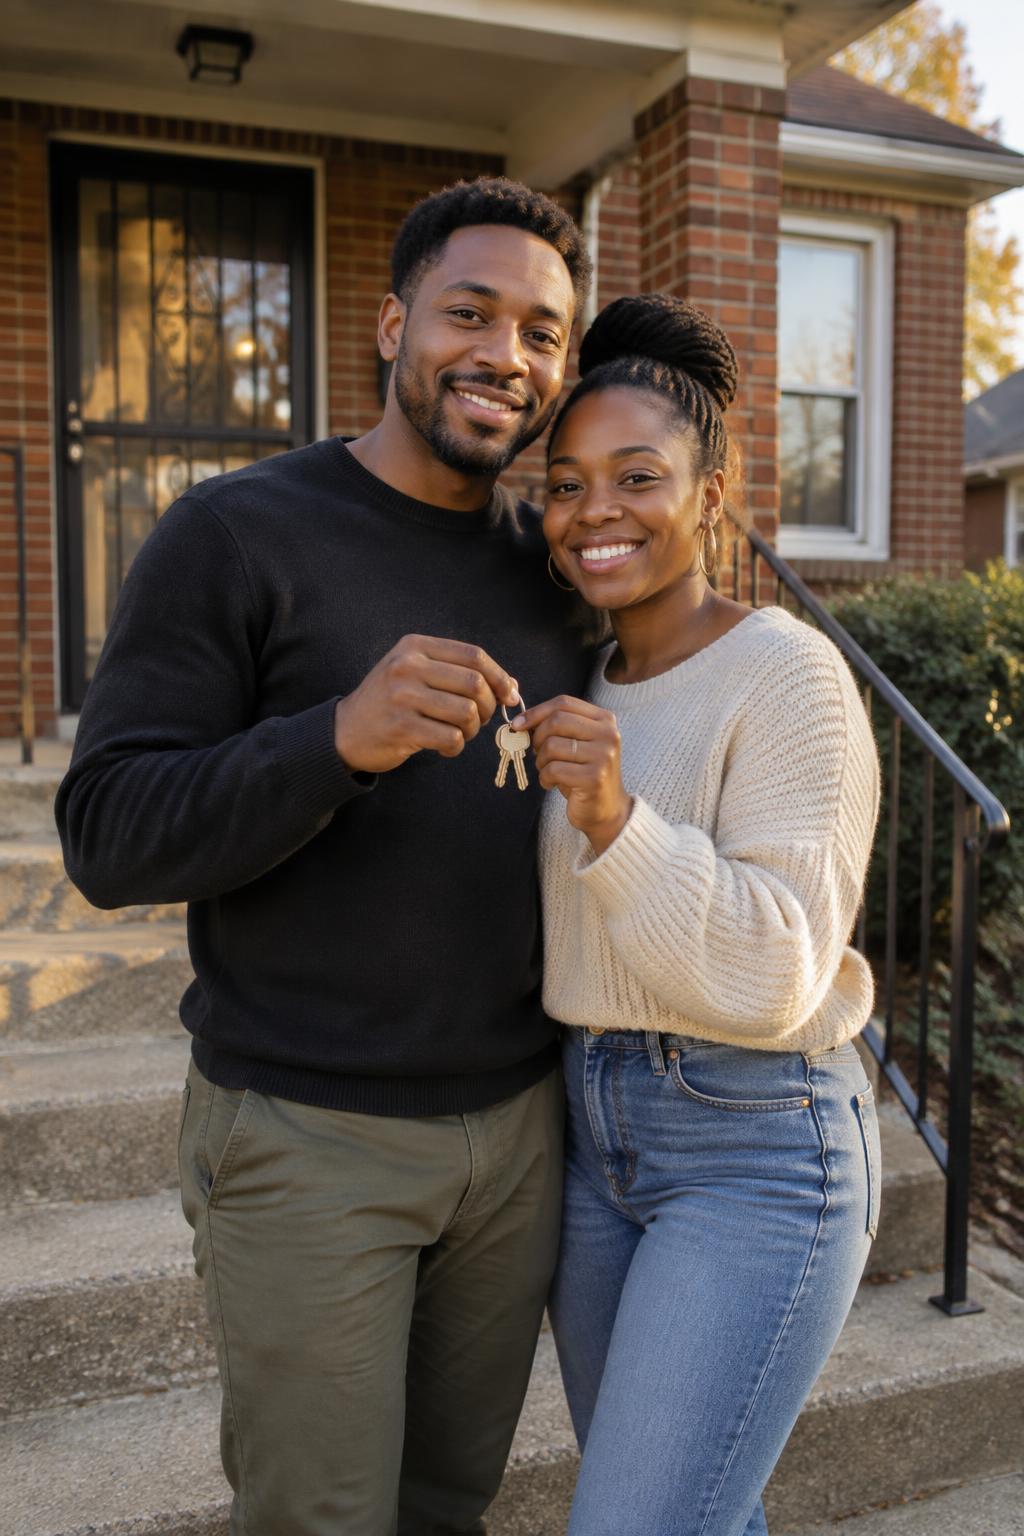
The moment it’s worth
Every one of these started with a single phone call.
What the call is like
No pitch. Just an honest look at your numbers.
A lot of first-time buyers tell me they felt embarrassed to call a lender. That they assumed they’d be told no before they even finished their sentence. So let me take that off the table right now.
On our call I’ll ask what you earn, what you owe, what you’ve saved and roughly when you want to buy. That is it. You’ll hang up knowing approximately what you can afford, which loans fit your situation, and whether any of Michigan’s down payment assistance programs apply to you.
If you’re not ready yet, I’ll say so — and I’ll tell you exactly what to work on and when to call me back.
Three steps
How this works, from here to your keys.
You reach out
Leave your name and number. That is the whole ask. No forms to fax, no credit check, no account to create, and nobody selling your information.
We talk it through
James calls you and you talk like two people, not a script. What you earn, what you owe, what you have saved, and what you actually want. He tells you plainly what you can afford — and what you will not be able to, which matters just as much.
You get pre-approved and we go find your home
He gathers your documents, gets you a real pre-approval letter, and walks you step by step to closing day. One name, one number, from the first call to the keys.
Straight answer
Who this call is for — and who it isn’t.
This is probably for you
- You are buying your first home and nobody in your family has done it recently
- You assume you need perfect credit or 20% down — and you have never had anyone check
- You are stably employed in or around Metro Detroit and ready in the next few months
- You want straight answers and you hate being sold to
This one isn’t
- You are looking for the fastest possible close on an investment flip
- You already have a lender you trust and just want a rate to compare
- You want a hard sell. James will not do it, and you will not get one
And if you’re somewhere in between — credit not great, savings thin, timeline uncertain — that is genuinely the most common call I take. Book it anyway.
Asked every single week
The questions first-time buyers always ask.
What credit score do I actually need?
It depends on the loan, and the honest answer is lower than most people fear. FHA generally accepts lower scores than Conventional, and VA is often the most flexible of all for eligible buyers. Below the minimum is not the end either — sometimes a few months of specific work changes what you qualify for, and James will tell you which moves actually matter.
How much down payment do I really need?
Less than you have probably been told. FHA starts at 3.5% down, Conventional can go as low as 3% for eligible first-time buyers, and VA can be zero down. On top of that, Michigan down payment assistance programs can help cover your down payment and closing costs — and most people who assume they cannot afford it have never been told those exist.
How long does the whole thing take?
The pre-approval is usually days, not weeks, once your documents are in. From accepted offer to keys is commonly around 30 days for a clean file. The part that takes as long as you want it to is the house hunting — some people buy the first home they tour, some look for months.
Does talking to you cost me anything or hurt my credit?
Neither. The first call is free and there is no obligation. A pre-approval does involve a credit pull, but that only happens once you decide to move forward and James tells you first.
James Cox, The Loan Strategist
Ten minutes now could change what you think is possible.
Tell me your name and number and I’ll call you personally. If it turns out you’re not ready yet, you’ll still leave the call knowing exactly where you stand. That part is free either way.
Serving Wayne, Oakland and Macomb counties · Independent broker sponsored by The Loan Factory